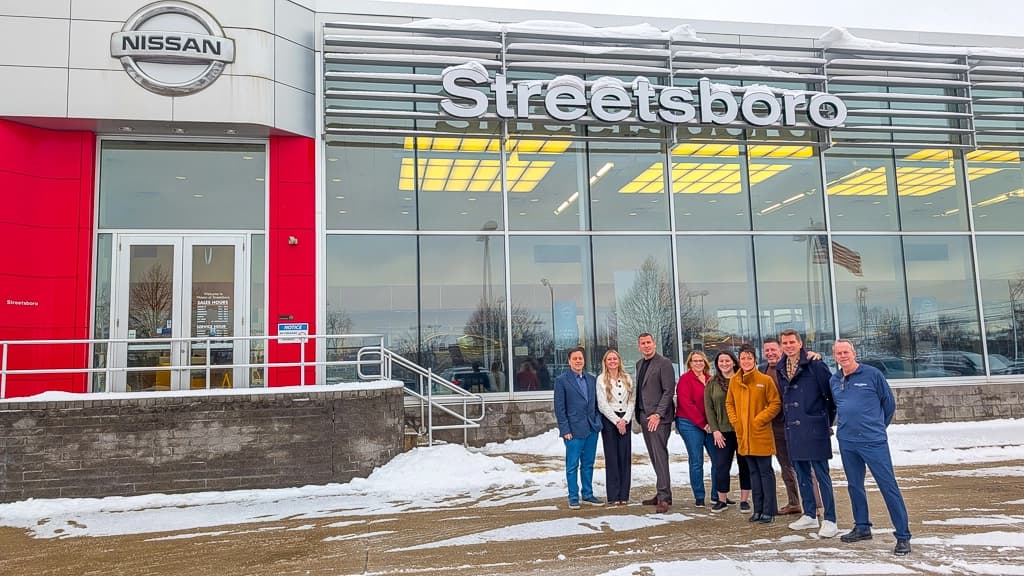
Storefront at the Streetsboro, Ohio store, a Coleman Automotive dealership. Like a franchise agreement with its addenda, a fund's core contract is often supplemented by investor-specific agreements. Photo: Sweet Dreams US LLC
Side Letters and MFN Provisions: How Sophisticated LPs Negotiate Beyond the LPA
In institutional private equity, the limited partnership agreement is rarely the whole deal. Side letters and most-favored-nation clauses are how large investors tailor their terms — and how the industry has tried to keep that process fair.
In the previous chapter, we described the limited partnership agreement as the document that controls a fund's economics and governance. In institutional private equity, that is true — but it is not always the complete picture. Alongside the LPA, many funds enter into side letters: separate agreements between the fund (or its general partner) and a specific investor that add to, clarify, or modify how the LPA applies to that investor.
Side letters are a routine feature of large institutional funds, where pension plans, endowments, sovereign wealth funds, and insurance companies each bring their own legal, regulatory, and policy constraints. They are also a source of legitimate concern for other investors, because a term granted to one limited partner may affect the others. The industry's answers to that concern — most-favored-nation provisions, disclosure norms, and regulatory scrutiny — are worth understanding for any investor evaluating a private fund.
This chapter walks through what side letters typically cover, how MFN clauses work in practice, the guidance published by the Institutional Limited Partners Association, and the recent history of SEC rulemaking on preferential treatment. It describes industry practice in general and is not a description of any term offered by the Fund. It is general education, not legal advice; the Fund's actual terms are governed solely by its offering documents.
What a Side Letter Is — and Why They Exist
A side letter is a contract. It is typically signed at the time an investor subscribes and sits alongside the subscription agreement and LPA. The LPA itself usually authorizes the general partner to enter into side letters and provides that their terms will govern for the investor that receives them, notwithstanding contrary LPA provisions. That authorization is important: a side letter can change how the fund treats one investor without amending the agreement that binds everyone.
Side letters exist mostly because investors are not uniform. A public pension fund may be subject to state open-records laws that require special handling of confidential information. A tax-exempt investor may need assurances about how the fund will manage exposure to unrelated business taxable income. An investor subject to ERISA may need commitments about plan-asset status. A foreign sovereign may need to preserve immunity. A university endowment may have a policy excluding certain industries. None of those needs can be addressed efficiently in a single LPA that governs everyone, so they are handled investor by investor.
What Side Letters Typically Contain
Industry practice groups side letter terms into a few broad categories. The first, and most common, are regulatory and legal accommodations — provisions that let an investor comply with laws and policies that apply to it. These include confidentiality carve-outs for public disclosure obligations, tax-related covenants, sanctions and anti-corruption representations, and excuse rights that allow an investor to opt out of specific investments that would violate its policies.
The second category is information and reporting rights: more frequent or more detailed reporting, specific data for the investor's own regulatory filings, access to portfolio-level information, or the right to meet with the manager periodically. The third covers governance — for example, a seat on the limited partner advisory committee (LPAC), consent rights over transfers to affiliates, or notice of key personnel changes. The fourth is economic: management fee discounts or offsets, often tied to commitment size or to participation in a first close, and rights to be offered co-investment opportunities. Economic terms draw the most attention because they directly affect how returns are shared across the investor base.
Even terms that look administrative can matter to other investors. An excuse right, for example, means that when one investor sits out a particular deal, the remaining investors fund a larger share of it and carry more concentration in that position. Enhanced information rights can give one investor an earlier or fuller view of portfolio developments than others receive — a meaningful asymmetry if the fund offers any liquidity or transfer opportunities. A fee discount for one investor does not usually raise the fees others pay, but it does change the sponsor's economics and, in some structures, how aligned the sponsor is with different groups of investors. This is why the industry discussion focuses less on whether side letters should exist and more on whether other investors can see what has been granted.
By the Numbers
Common Side Letter Provisions in Institutional Funds
Regulatory accommodations — public-records confidentiality, ERISA, tax, sanctions, sovereign immunity
Excuse rights — opting out of investments that conflict with an investor's legal or policy restrictions
Information rights — enhanced or customized reporting and access to the manager
Governance — LPAC seats, notice of key person events, transfer consents
Economics — fee discounts tied to size or first-close participation; co-investment offer rights
MFN — the right to elect terms granted to other investors, subject to defined carve-outs
How Most-Favored-Nation Clauses Work
A most-favored-nation (MFN) provision is itself a side letter term. It gives an investor the right to review the side letter terms granted to other investors and to elect to receive some or all of them. The concept is simple; the mechanics are not. In most institutional funds, MFN rights are tiered by commitment size. An investor that commits a given amount can typically elect any term granted to investors with equal or smaller commitments, but not terms granted to larger investors.
MFN clauses also come with carve-outs — categories of terms that cannot be elected regardless of size. Common carve-outs include provisions tied to an investor's specific legal, regulatory, or tax status (which would make no sense for another investor to elect), LPAC seats, terms granted to the manager's affiliates or employees, co-investment rights, and economic terms tied to participation in an early close. The election process usually runs after the final close: the manager circulates a compendium of eligible side letter terms, often without identifying which investor received them, and each MFN holder has a window to make its elections.
Consider an illustrative example. Suppose a fund grants Investor A, committing $50 million, a 10-basis-point fee reduction, and grants Investor B, committing $25 million, quarterly portfolio-level reporting. Investor C, committing $30 million with an MFN, could typically elect B's reporting rights (granted to a smaller investor) but not A's fee reduction (granted to a larger one) — unless the fee term was given for a first-close commitment and carved out of MFN entirely. The outcome depends entirely on how the MFN clause is drafted, which is why sophisticated investors negotiate its wording as carefully as any economic term.
ILPA's View: Transparency First
The Institutional Limited Partners Association is the leading trade body for institutional private equity investors. Its ILPA Principles, most recently revised as Principles 3.0 in 2019, set out the association's recommended best practices on fund terms, governance, and transparency. On side letters, the core message is disclosure. ILPA encourages managers to disclose the existence and terms of side letters to all investors, to provide MFN rights broadly, and to keep carve-outs narrow and clearly defined. ILPA has also published a Model Limited Partnership Agreement and standardized reporting templates designed to reduce the need for investor-by-investor customization in the first place.
ILPA's guidance is voluntary — it is not law — but it shapes negotiations across the institutional market. It also reflects a practical reality: the more terms that are customized privately, the harder it becomes for any one investor to know whether it is being treated fairly. Transparency and well-drafted MFN rights are the market's attempt to keep side letters from becoming a hidden two-tier structure.
The SEC, the Private Fund Adviser Rules, and the Fifth Circuit
In August 2023, the SEC adopted a package of rules under the Investment Advisers Act aimed specifically at private fund advisers. One component, the preferential treatment rule, would have prohibited advisers from granting certain preferential redemption rights and certain preferential information rights that the adviser reasonably expected to have a material negative effect on other investors, unless offered to all investors. It would also have required advisers to disclose other preferential treatment to current and prospective investors.
Those rules never took full effect. In June 2024, the U.S. Court of Appeals for the Fifth Circuit, in National Association of Private Fund Managers v. SEC, vacated the private fund adviser rules in their entirety, holding that the SEC had exceeded its statutory authority in adopting them. The SEC did not seek further review. As a result, there is no SEC rule specifically prohibiting or mandating disclosure of side letter terms for private funds.
That does not mean side letters are unregulated. The general antifraud provisions of the Advisers Act, including Rule 206(4)-8, which prohibits misleading statements to investors in pooled investment vehicles, continue to apply. The SEC has brought enforcement actions where advisers granted preferential terms to some investors without adequately disclosing them to others, and examination staff have repeatedly listed private fund conflicts and disclosures among their priorities. The practical standard has not changed much: preferential terms that could matter to other investors should be disclosed.
Questions Worth Asking Any Sponsor
Side letters and MFN clauses are most relevant in large institutional funds with many investors of very different types. Smaller funds and co-investment vehicles often take a simpler approach. Whatever the vehicle, an investor can reasonably ask a few questions: Does the governing agreement permit side letters, and on what terms? If side letters exist, are their terms disclosed to all investors? Are there any economic or information rights that differ between investors? Is there an MFN mechanism, and what are its carve-outs?
The answers belong in the offering documents or in written responses from the sponsor — not in a conversation. As with every other term, the governing agreement and any written disclosures are what control, and your own counsel is the right person to help you evaluate them. It is also worth remembering that a side letter's protections run only to the investor that signs it. If a provision matters to you, the question is not whether some investor in the fund has it, but whether the documents you sign give it to you.
Prime Insight
This chapter describes how side letters and MFN provisions generally work across the private equity industry. It is not a description of the Fund's terms.
Questions about how the Fund treats investors, including any investor-specific arrangements, are answered by the Fund's offering documents, and our team will respond to them in writing.
We encourage every prospective investor to review those documents with independent legal counsel before investing.
Prime Dealer Equity Fund is a private equity vehicle co-investing with Coleman Automotive Group in the acquisition and optimization of automotive dealerships across the United States.
For qualified investor inquiries:
→ Contact our investor relations team