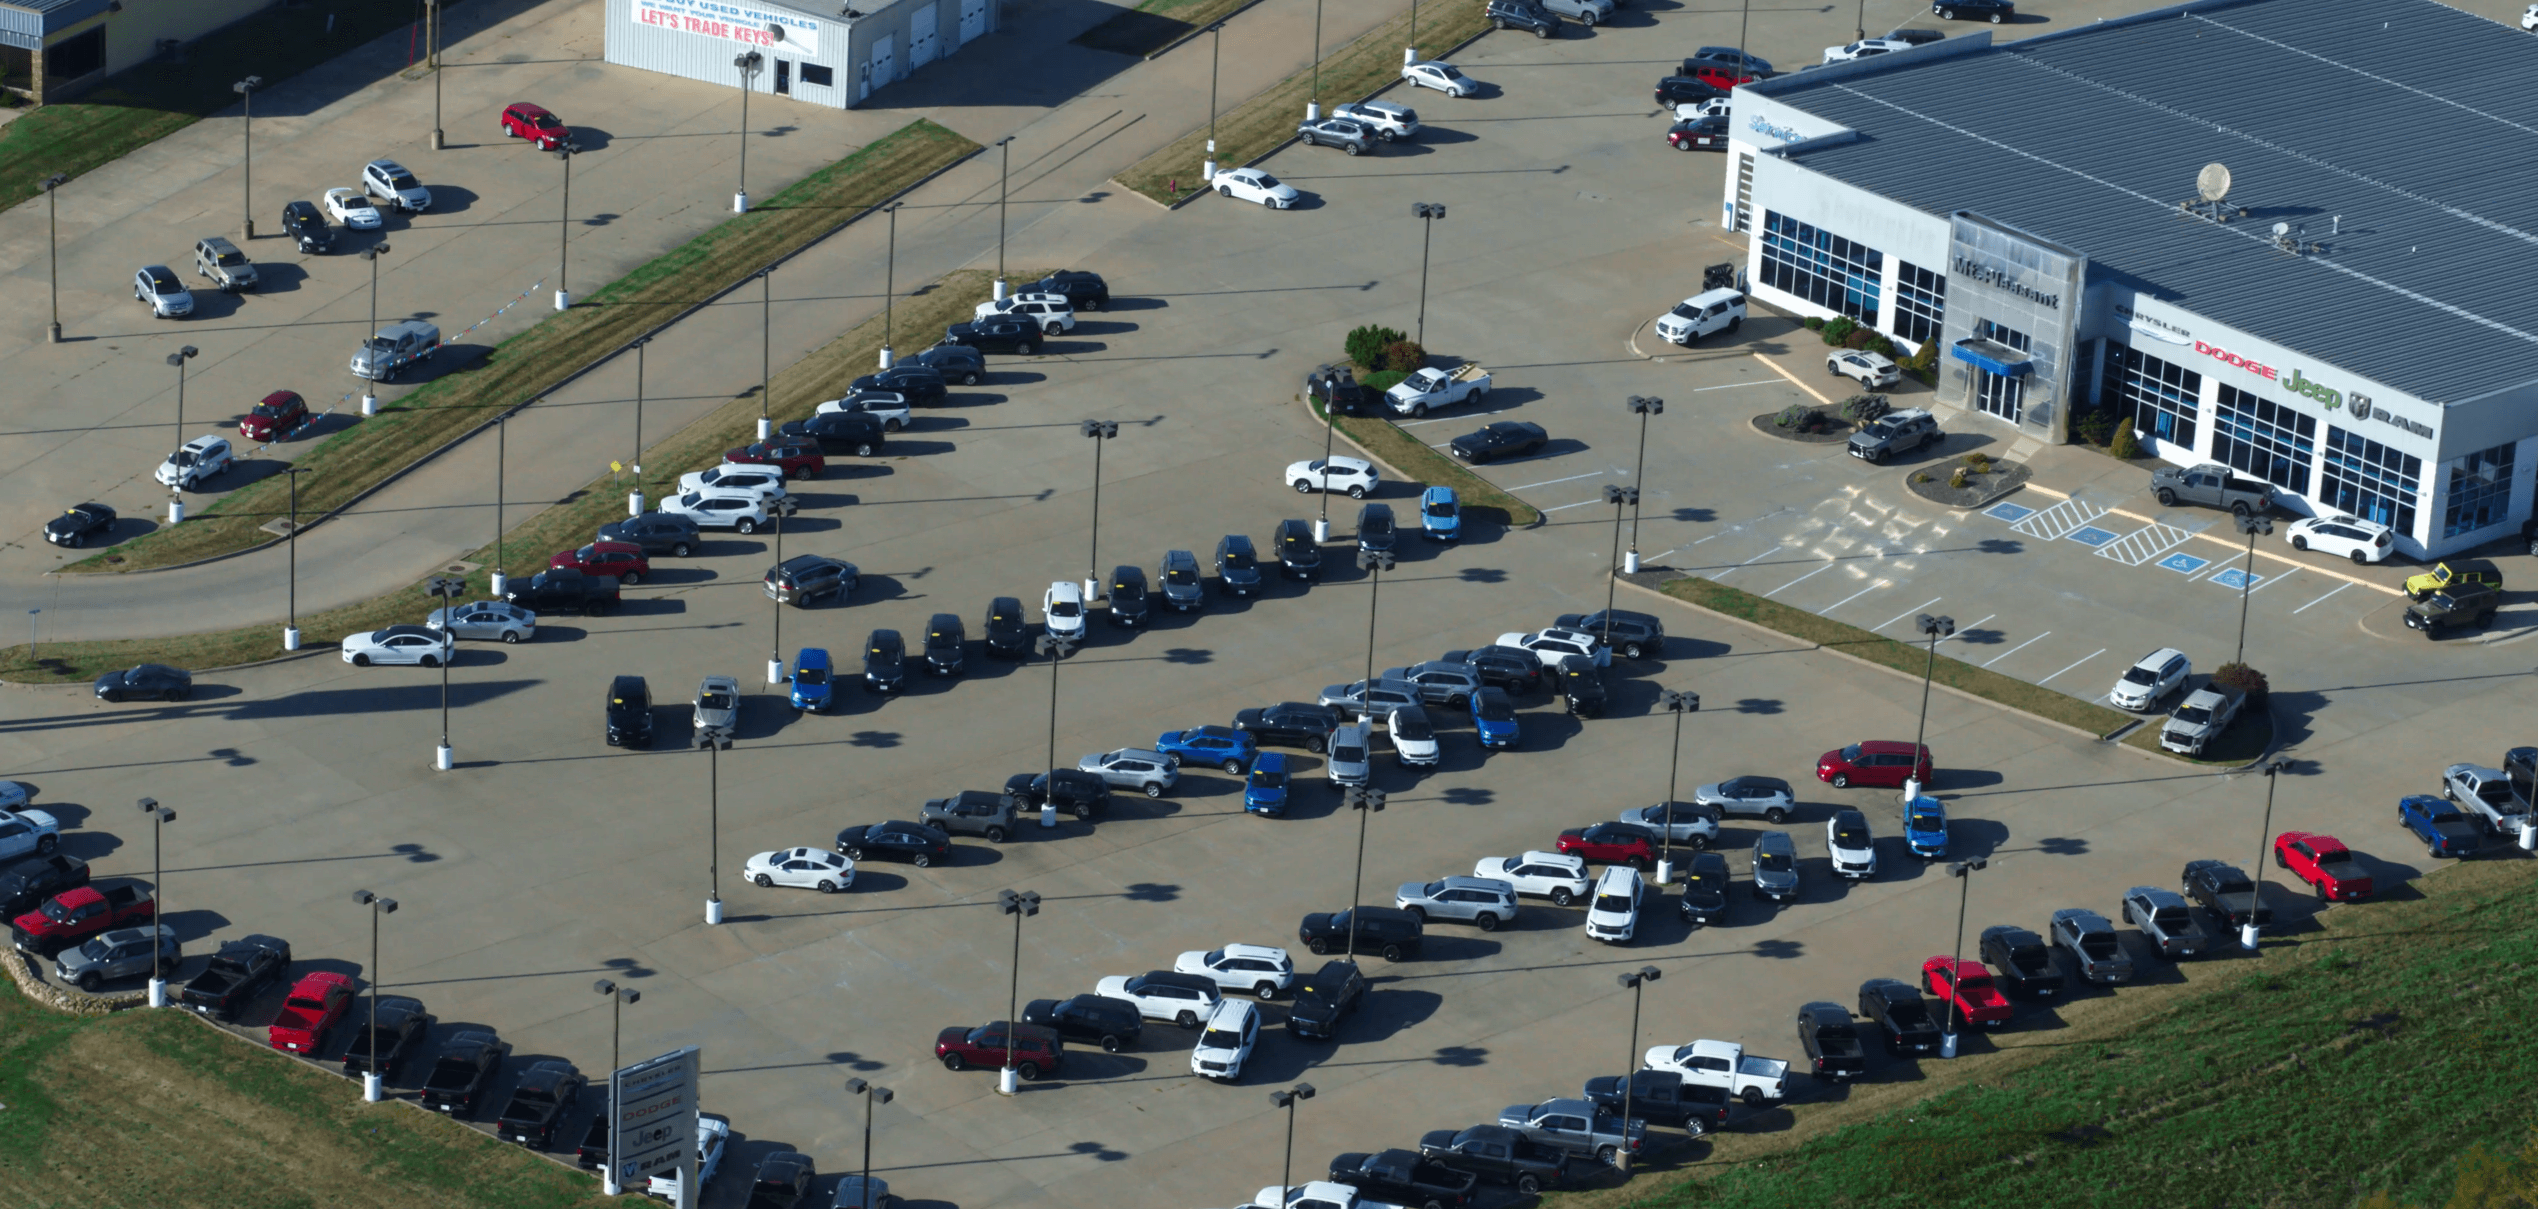
Aerial view of Mt. Pleasant Chevy GMC CDJR in Iowa, a Coleman Automotive dealership. A multi-brand campus like this one carries parts inventory for several manufacturers — each with its own stocking, ordering, and return rules. Photo: Sweet Dreams US LLC
The Parts Inventory Discipline: Fill Rate, Obsolescence, and Turns
A parts department is an inventory business sitting inside a service business. Stock too little and technicians wait while customers leave. Stock too much and capital sits on shelves until it becomes obsolete. The discipline lies in managing the tension between the two.
In Module 1 we spent a full chapter on vehicle inventory — days supply, turn rate, and the cost of aged units. There is a second inventory inside every franchised dealership that gets far less attention, even from experienced investors: the parts department. It may hold several hundred thousand dollars or more of stock across thousands of individual part numbers, and it behaves according to the same underlying logic as the vehicle lot. Capital tied up in inventory has a cost. Inventory that does not move loses value. And inventory that is not there when it is needed costs a sale.
The parts department sells in three directions. It supplies the dealership's own service department — the largest channel at most stores. It sells over the counter to retail customers and do-it-yourselfers. And it sells wholesale to independent repair shops, collision centers, and fleet operators. Each channel has different margin and service expectations, and each depends on the parts manager having the right part on the shelf at the right time.
This chapter walks through the three metrics that define parts inventory discipline — fill rate, turns, and obsolescence — how they pull against one another, the stocking and return mechanics that manage that tension, and how Coleman Prime evaluates a parts department during diligence.
Fill Rate: Having the Part When It Is Needed
Fill rate measures the share of parts requests that can be filled immediately from stock. Most operators focus on first-time fill rate — the percentage of lines on a repair order or counter ticket that are filled from the shelf on the first request, without a special order or a run to another dealer. A technician who walks to the parts counter and gets the part in hand keeps working. A technician who is told the part will arrive tomorrow stops, the vehicle sits in a bay or on the lot, and the customer gets a call they did not want. The cost of a poor fill rate extends well beyond the parts department. Every unfilled request costs technician time, ties up a service bay, delays the repair order, and puts customer satisfaction at risk. On flat-rate pay plans, as we discussed last week, technicians waiting on parts are technicians not earning — and that frustration shows up in retention. For wholesale customers, fill rate is the reason they buy from the dealer at all. An independent shop that cannot get the part today will find another source.
Many well-run departments target first-time fill rates in roughly the high-80s to low-90s percentage range for service and counter demand. A department far below that is usually understocked on common parts or has poor stocking rules. A department claiming fill rates near 100% should be examined carefully: it may be carrying far too much inventory to get there, or it may be measuring fill rate in a way that excludes special orders from the calculation.
Turns: Making the Inventory Work
Inventory turns measure how many times the department sells through its average inventory over a year, usually calculated as annual cost of parts sold divided by average inventory value at cost. For example, a department with $1.2 million in annual cost of sales and an average inventory of $250,000 turns its stock roughly 4.8 times a year. Put differently, the average part sits on the shelf for about 76 days before it sells. Higher turns mean less capital tied up for the same level of sales. Industry guidance commonly places a healthy stocking-inventory turn rate in the range of roughly four to six times a year, though the right target depends on the brand, the store's volume, and how far it is from the manufacturer's distribution center. A store that receives daily parts deliveries can run leaner than a rural store that receives fewer shipments and needs deeper stock to protect fill rate.
Turns also need to be read carefully. A department can show strong turns by stocking very little and special-ordering everything — which looks efficient on the inventory line and costs heavily on the service side through poor fill rate. That is why turns and fill rate must always be read together. Either number in isolation can be manipulated; the two together tell the truth.
By the Numbers
An Illustrative Parts Department
For example: $1.8M annual parts sales at a 35% gross margin → about $1.17M cost of sales
Average inventory at cost: $260,000 → roughly 4.5 turns, about 81 days on the shelf
First-time fill rate: 88% of service and counter lines
Parts with no sale in 12+ months: $36,000, about 14% of inventory value
Every $50,000 of idle stock cleared and not replaced frees $50,000 of working capital and removes a future write-down risk
Obsolescence: The Quiet Balance-Sheet Problem
Obsolescence is what happens when inventory stops moving. Parts are superseded by new part numbers. Models age out of the market. A part ordered for a single repair is returned unused and goes back on the shelf, never to be called for again. Over time, these parts accumulate. They are still carried on the balance sheet at cost, but their real value is often a fraction of that — and sometimes close to zero. Parts managers typically track inventory by aging bucket: parts with no sale in the last three, six, nine, and twelve months. Parts in the older buckets are frequently described as idle or obsolete stock. A meaningful percentage of inventory in the twelve-months-plus bucket is a signal that stocking rules have been loose, that returns have been neglected, or that the department has absorbed inventory from discontinued programs without addressing it.
For an investor, obsolescence is a balance-sheet question as much as an operating one. A dealership's financial statement may show parts inventory at its carrying value, but a buyer acquiring that inventory needs to know how much of it will actually sell. In acquisition diligence, parts inventory is typically counted and valued as part of the transaction, and obsolete stock is a common point of negotiation. We will return to this in our chapter on quality of earnings.
Phase-In and Phase-Out: The Stocking Rules
The mechanism that balances fill rate against turns and obsolescence is the stocking policy — the set of rules that determine when a part is added to stock and when it is removed. Most dealer management systems and OEM parts programs support phase-in and phase-out criteria based on demand history. For example, a part might be added to regular stock after it has been requested a certain number of times within a defined number of months, and removed from stock when it has not sold within a longer window.
A key input to those rules is lost-sale tracking. When a technician or counter customer asks for a part that is not in stock, a disciplined parts department records that request even if the part is special-ordered or the customer goes elsewhere. Without this data, the stocking system only sees demand that was successfully filled, and it systematically understocks parts the store needs. Lost-sale tracking is one of the simplest and most overlooked tools in parts management.
Manufacturers also provide stocking guidance and, in many cases, automated replenishment programs that recommend or place orders based on the dealer's sales history and the OEM's view of regional demand. These programs can be valuable, particularly for new model launches, but they need oversight. A parts manager who accepts every system recommendation without review can find the department carrying inventory sized to the manufacturer's preferences rather than the store's actual demand.
Returns: The Release Valve
Most manufacturers offer dealers some form of parts return program — the ability to send back eligible, unsold stock for credit, typically up to a percentage allowance tied to the dealer's purchases over a period, and often subject to restocking charges and eligibility rules. The specifics vary by manufacturer and change over time. What does not vary is the principle: return allowances that go unused are a lost opportunity to clear slow-moving inventory at or near cost.
Disciplined departments treat the return window as a scheduled event. Before each return period, the parts manager pulls the aging report, identifies eligible slow movers, and uses as much of the allowance as is sensible. Parts that are not returnable are worked through other channels: discounted to wholesale customers, offered to other dealers through parts-locator and exchange networks, or written down when there is no realistic market. The goal is to keep the older aging buckets small and stop obsolescence from compounding year after year.
Gross Margin and the Channel Mix
Parts margin depends heavily on which channel the sale goes through. Parts sold on customer-pay repair orders generally carry the strongest margin. Warranty parts are reimbursed by the manufacturer, and as we touched on in our labor rate chapter, many state franchise laws tie warranty parts reimbursement to the dealer's retail markup under a statutory formula. Wholesale parts sold to independent shops and collision centers carry lower margins but can add meaningful volume, and in some markets wholesale is a significant share of the department's sales.
Pricing matrices play the same role in parts that labor-rate matrices play in service. Many departments price customer-pay parts on a sliding markup — higher percentage markup on low-cost items, lower markup on expensive components — to stay competitive on big-ticket parts while earning appropriate margin on the small items that make up most transactions. As with labor rates, a matrix that is designed deliberately and reviewed regularly will usually outperform a single flat markup applied to everything.
How Coleman Prime Evaluates a Parts Department
In diligence, we review the parts inventory aging report, the current stocking and phase-out rules, first-time fill rate by channel, turns, gross margin by channel, and the store's use of manufacturer return allowances over recent periods. We compare the carrying value of inventory to what an aging analysis suggests it is realistically worth, and we treat material obsolete stock as a valuation item in the transaction rather than an operating afterthought. We also look at how the parts and service departments work together — because the most common source of poor fill rate is not the parts manager alone, but a lack of communication between the parts counter and the service drive.
A well-run parts department is not glamorous. It is a set of rules, reports, and habits applied consistently every week. But it is also one of the clearest windows into a dealership's overall operating discipline. A store that knows exactly what is on its shelves, why it is there, and how fast it moves is usually a store that manages the rest of the business the same way. Next week, we close Module 3 with warranty administration — where parts, labor, and manufacturer reimbursement all come together.
Prime Insight
Coleman Prime reviews parts aging, fill rate, turns, and return-allowance usage as part of operational diligence on every acquisition target.
Obsolete and idle parts inventory is valued realistically and addressed in the transaction rather than inherited at carrying value.
After acquisition, stocking rules, lost-sale tracking, and scheduled returns are managed under the Coleman Automotive Group fixed-operations playbook, with fill rate and turns reviewed alongside service performance.
Prime Dealer Equity Fund is a private equity vehicle co-investing with Coleman Automotive Group in the acquisition and optimization of automotive dealerships across the United States.
For qualified investor inquiries:
→ Contact our investor relations team